- Adomako, S., et al. (2016).
- Ammann, M., et al. (2012).
- Arianti, B. F. (2018).
- Awais, M., et al. (2016).
- Barber, B. M. and T. Odean (2001).
- Blue, L. (2016).
- Bonds Raacke, J., & Raacke, J. (2012). Research methods: Are you equipped?, Prentice Hall.
- Bryman, A., & Becker, S. (2012).
- Casanova, R., et al. (2011).
- Engle-Warnick, J., et al. (2016). Trust, ambiguity, and financial decision- making, CIRANO.
- Fitra, H., Rasyid, R., & Susanti, Y. (2018, July 2). The Influence of Locus of Control and Financial Knowledge to Employee Investing Decision PT. Pertamina (Persero) Branch of Padang. Atlantis Press.
- Ghauri, P. N., & Grønhaug, K. (2005). Research methods in business studies: A practical guide, Pearson Education.
- Henderson, B. J. and H. Tookes (2012).
- Janor, H., et al. (2017).
- Johnson, R. B., & Onwuegbuzie, A. J. (2004).
- Kefela, G. T. (2010).
- Khan, S. (2016).
- Kumar, S., et al. (2017).
- Nguyen, L., et al. (2016).
- Ritter, J. R. (2003).
- Saunders, M., et al. (2007).
- Shusha, A. A. (2017).
- Spaniol, J., & Bayen, U. J. (2005).
- Visyalini, S. (2018). Financial literacy education and retirement planning of the urban elderly in Malaysia/Visyalini Selvadurai, University of Malaya. 1-298.
Abstract:
As an individual investor, it is incredible to have a successful performance return without financial knowledge. An organization’s performance must be measured and analysed based on an adequate financial management system. In today’s multifaceted financial scenery Financial Literacy is crucial as it does not only impact financial decisions at the business level but is also important for the country’s development. Financial literacy has the importance of the backbone of society. The study adds a new mechanism of financial literacy. The main objective of this study is to determine further insight into the role of financial literacy on an individual’s behaviour and attitude towards financial decision making. For analysis, the moderator impact of financial literacy on decision-making data of 100 individual investors has been collected from different banking sectors of Pakistan. The result of this study shows that financial literacy has a significant impact on financial decision making. This study delivers knowledge that can contribute to guiding coming studies, making policies, directors and instructors in their teaching.
Key Words:
Financial Literacy, Financial Behaviour, Investment Decision Making, Financial Attitude
Introduction
Does financial literacy distress financial behaviour? Is it correct if the public studies financial works, they can make a better financial decision? How does financial behaviour distress the financial decisions of people? If the answer is yes, do the school or college students apply those influences in actual life as sophisticated persons? It was not probable to live in present creation deprived of being financially well-educated
(Casanova, Espeland et al., 2011).
An individual’s skill to achieve his individual capital goal has to convert significant matter in today’s world. The public currently is watching at diverse facets of their financial matters. They not only watched their short time matters but also, keep an eye on the long-time matters as well. For instance, individuals give attention to their superannuation tactics, their kid's schooling, household forthcoming, and alike objects. In addition to investment decisions, nowadays, people make significant verdicts concerning their bases of money. When money is desirable, an individual may pursue to take debt from the bank or other money facility giver such like credit card or from the friend or family person. The enlarged difficulty of the budget, financial marketplaces and their rules estimate approaches, and obtainability of dissimilar financial items have produced a solid change to research and analyse financial knowledge between school and college pupils, as well as stakeholders and authorities.
The influence of less financial literacy is further overwhelming in emerging frugality, where entree to financial facilities and the variety of facilities given is abundant extra imperfect and customer guard negligible. Short financial literacy might take to bad financial decision-making, with terrible results. At what time in a person’s life would one start to acquire about financial stuff? Preferably, it should start when one starts to make business choices, frequently upon send-off house. School and university pupils essential to have information and assistance to achieve their expenditures and money that can be from family or scholarship from the college or university.
(Kefela 2010). Exposed that financial literacy is straight related with self-beneficial financial behaviour and so financial information programs must take a healthy viewpoint to contain the basics of finance meanwhile deprived of empathetic the main finance ideologies, annuity knowledge will be unsuccessful. Research proves to be appreciated as it has exposed this influence as well. Financial knowledge, which is also connected with the proficiency of factors such as inflation, compounding interest and diversification of risk, as the analysis of these aspects also assistances to go for suitable decisions. (Awais, Laber et al. 2016)
The investment behaviour of an individual is a developing part of behavioural finance. Behavioural finance emphasis on person’s metal influences, which subsidizes operative decision making (Ritter 2003). Investors usually capitalize with the assistance of societal connections. Standards impact stakeholder decision making. Today internet transaction also rises single investors generally do transactions with the assistance of the internet (Barber and Odean 2001).
(Spaniol and Bayen 2005) According to him mental assistances of investors are an extra limitation that enhances persons financial decision making. Another important behavioural phenomenon is the disposition effect. (Henderson and Tookes 2012) According to him, there are many researches about the natural outcome that national investors are disinclined to trade resources at damage relating to the worth at which they are buying this benefit. Nature result is the propensity of an investor to trade victors too primary, and grip failures also extended. (Ammann, Ising et al. 2012) accomplish that executives who have a minor nature result invest extra in bigger equities with advanced business size, an advanced previous going and a complex danger familiar act. But, the financial situation and money feature one account for a portion quantity of the change in the disposition result transversely joint capitals.
Financial knowledge might be gainful for humanity as an entire, as well as for the countries’ attractiveness, falling economic barring hazards, growing well-informed behaviours and causative to bigger liquidness for the economic marketplaces. In a 2008 determination, the European Assembly enquired for the development of customers’ knowledge and compassion to money and particularly praised matters. Dissimilar Western republics understood, additional or fewer, how significant it is to grow a strategy of economic information. England related republics appear to be improved ready, though European Union efforts to execute a convinced lively for the Mainland Europe. A novel idea established, that of economic knowledge, in the similar method we conversation about knowledge in overall, or about computer knowledge, data knowledge.
Financial literacy or financial education can largely be clear as “giving awareness with a considerate of all financial market products, particularly income and dangers, for making the right decision”. Observed from this viewpoint, financial education mostly relies on individual investors to authorize people to take active performance to progress their financial happiness and make them save from suffering in cases that are economical. Financial literateness goes outside the facility of economic info and guidance. The emphasis of any argument on financial knowledge is mainly on the separate, who typically has partial capitals and assistance to raise the difficulties of financial businesses with financial mediators on an everyday root. Investment is clear as the procedure of purchase of financial products or further things of worth with confidence of their better future income. Also, saving is well-defined the tactic by which the money is saved away for taking a return hope in future moderately minor in contrast to venture. Saving and investment behaviour has continually remained a very variance in the purposes of financial literacy programmes in the advanced and emerging countries has stayed a critical principle for the introduction for trade stakeholders for making an investment decision. In advanced countries, financial knowledge is related to customer defence. Well info exposes, they trust, would go an extensive means in establishment supervisory morals for customer defence.
Literature Review
The significance of Financial Literacy in financial decision making as emphasized in the report of The World Bank, comprise I) assistances to make consumers for hard financial periods by encouraging approaches that ease risk such as gathering savings, spreading assets and buying insurance. ii) supports behaviours such as appropriate payment of bills and escaping of over obligation which assistance consumers to keep their access to loans in close-fitting credit markets. iii) serious for promoting access to finance by producing encouragements and atmosphere that indorse wanted financial behaviours.
(Kumar, Watung et al. 2017) This research practical, measurable technique with 337 trials as respondents occupied from President University students. Research practical suitability sampling method. They conclude that financial behaviour is impacted by financial knowledge and that will affect to financial choice of kids, so paternities must give decent understanding about financial stuff to their children that might distress to kids’ financial behaviour and the decision that they will be made after that. The result of this research is appreciated and can benefit education organizations that come from any related to raise the financial knowledge of college or university students.
(Adomako, Danso et al. 2016). This research makes to present financial knowledge as a moderator of the association between easy availability to finance and firm progress. They collected the data from 201 small and medium firms in Ghana. Their experimental conclusions recommend that financial knowledge improves the easy availability to investment and firm development associations. And they suggest that the managers of the firms should learn the financial management process that will be helpful in the growth of the firm in a strong way of; this study finds out the influence of financial knowledge on personal capital management. To find out this thing, he made a structured questionnaire to collect the data from the workers of the Bank of Baroda located in Kenya. He used the descriptive method to find out the results. Questionnaire distributed among the 173 workers of the bank 64 respondents was the middle and senior workers of the bank. To assess financial literacy and its effect on the personal finance management of employees of a bank, The finalized questionnaires were tested with the help of SPSS software. Analysis of variance finds out from dependent and independent variables of the data. The research found that financial knowledge strongly affects the personal capital management among the workers of the bank of Baroda, which takes to extreme maximum investment exercise. The absence of financial knowledge was showed to disturb the personal economic management of the workers of the bank of Baroda.
(Visyalini 2018). The key factors attentive in this research were demographic, economic defiance, financial knowledge and financial knowledge influences—this study practical together measurable and qualitative practice. Data was gathered from the survey and the interview. There was held two surveys; in the first survey, he interviewed 1239 individuals, and in the second one, he interviewed the 623 individuals of Klang valley. He used a simple random sampling method to collect the data. Results show that there was an optimistic association between age and relaxed superannuation. There was an optimistic association among gender and capital possession, relaxed superannuation, period of savings too, approximation superannuation investments, and financial preparation conduct. Furthermore, there was an optimistic association between society and relaxed retirement. He found a strong association between the knowledge and the possession of the assets and period of saving which last.
(Blue 2016). Knowledge about active behaviours to handle money is the first thing of 21st-century ability. Individuals considered have less financial knowledge whenever checked by the financial literacy plans/programs. In this research, the researcher found that financial literacy is not important for the individual only; it should be on community base program which helps not only the individual of that specific country but the whole community at the same time, which helps in the financial decision making.
(Khan 2016). The main aim of this research was to examine the financial knowledge and financial knowledge of persons and specialized investors who invest in the financial market to earn profit. He also tests the association of financial literacy and financial knowledge and the impact of risk factors that impact the investment decision. He used a questionnaire for collecting data for examining Rawalpindi and Islamabad investor 257 respondents responded to the questionnaire. He used correlation and regression with the help of SSPS software for analysis. The result shows that there is an important confident association among the financial knowledge, financial literacy and investment decision
(Fitra, Rasyid et al. 2018). This research intentions to regulate the result of Locus of Control and Financial literacy on Investment Decisions of people. They collected the data from PERTAMINA, which was the branch of Padang, and they got 43 respondents. Data was first hand-collected data which they collected with the help of a questionnaire. There exercise the different tests on data. They did regression analysis with the help of SSPS software. The outcomes exposed that the variable Locus of Control and Financial Information partly important impact on investment decision making of employees. The immediate exam outcomes also express that the variables of Locus of Control and Financial Information have an important effect on employee investment decisions.
(Shusha 2017) This study sample contains 386 respondents on behalf of diverse parts people of Egyptian; the key arithmetical approaches used to trial the study propositions were Pearson's association test and ranked regression investigation. The fallouts established that there were belongings of demographic features on economic hazard acceptance. Furthermore, the results confirmed that financial literacy moderates the relationships between demographic features of entities and their leaning to take risks. (Nguyen, Gallery et al. 2016). The main objective was to test the impact of risk acceptance features name: customer financial knowledge, customer trust in the advice of the agent and association with the facilities. For this research, they collected primary data of 538 from the customers of agents with the help of the survey method. Results show that risk tolerance and investment decision making have a strong positive association between them. Additional, customer trust and association span with the facility were completely connected with customer financial knowledge and risk tolerance.
(Engle-Warnick, Pulido et al. 2016). They tested the household people’s trust towards trust and its role in the investment. They found that trust has a positive impact on the decision making, investment and behaviour of individuals. They found that real confidence and the financial knowledge of people and strongly predict their behaviour. With the knowledge and trust, they make the right decision for the investment.
(Arianti 2018). This study intentions to analyse the effect of financial knowledge, financial behaviour and pay on investment decisions. He used the descriptive method, and they used primary data for this research. They collected the data from the 100 students with the help of a questionnaire which was distributed among them. He has done different tests apply on that data; he finds out t-test, f test, regression and correlation with the help of SSPS software. He concludes that financial literacy has not any impact on the investment decision, while he said financial behaviour has a strong impact on the investment decision because the behaviour of any person take to do something that he thinks.
(Janor, Yakob et al. 2017). They associate the Financial Literacy levels of two different countries Malaysia and the United Kingdom, by using the data of the survey with the help of a questionnaire made by the OECD. They conclude that the financial knowledge of both countries was low and governments of their countries to take some steps to spread the financial knowledge among the people. They also found out that different factors also impact the investment decision making, which was demographic, financial, societal and mental factors key factors that respect to financial literacy on investment decision.
Methodology
This section is designed to exact the facts of methodology and assumed actions to discourse the research question. Its additional frameworks are the argument on the research plan, research approaches, research policy, sampling, instrument and instruments used for data inspection. For that, data was collected from the individual investors of investment banking offering banks of Pakistan.
The opinion of research idea defines that how individuals react to an actual condition or situation (Johnson and Onwuegbuzie 2004). In practicality, it takes the opinion that people are probable to argue their understandings in the informally built atmosphere, and it is to be used totally on human focuses. This shows that practicality is extra related to business managing study. Mainly, the descriptive research plan tells the participants of respondents of the study (Bryman and Becker 2012). The determination to choose this research tactic for use is to define the landscapes of a populace being examined. Though, this study strategy does not discourse the queries about how, when and why these features happen.
Investigator strategy is mostly an investigation plan which wants to choose to carry out the research work (Saunders, Lewis et al. 2007). This study used a review grounded approach, and questionnaires were modified to get the responses.
Data Collection Method
Data always have two types primary and secondary. Primary data collect from direct bases, and it desires to collect the first time, and it needs to be managed, while the data which has previously been composed and analysed is called secondary data. This research is a quantitative-based study, so we are taking a survey-based research strategy, so first handed data on a survey-based questionnaire is suitable for this study.
Target Population
A whole list of all the fundamentals below attention is recognized as the target population. In this, the targeted population was 100 individuals’ investors of different banks of Pakistan.
Determining Tools
Investigators stressed that the survey must be built on an exact scale, influenced free and accurate queries should be comprised which rises its dependability and cogency (Bonds-Raacke and Raacke 2012). (Ghauri and Grønhaug 2005) reinforced the use of an inspection in the study. Also, they suggested using adapted questionnaires for their dependability and cogency have previously been verified. So, if it is possibly better to use an approved questionnaire. So, to get the replies, the current research has also used a modified questionnaire that contained numerous queries over which an effort is made to quantify the variables.
The questionnaire has four parts in the first part, there are five questions which are related to Financial Literacy, and the second part is related to Financial Behaviour consist of five questions third part of questions are about Financial Attitude and have five questions these three parts of the questionnaire with Likert Scale answering options of Strongly disagree, Slightly disagree, Neutral, Slightly agree and Strongly agree the last part of the questionnaire is related to Financial Trust, and it has four questions with answering options of yes and no. So altogether, there are nineteen questions to which respondents are going to respond. On which average will take, and the correlation will find to check the relation of variables Financial Behaviour, Financial Attitude, Financial Trust and moderator role of Financial literacy on the Decision making.
Findings and Discussions
This chapter included the found results
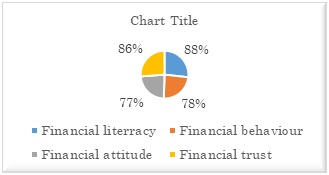
and proper discussion on that results. Financial knowledge, financial behaviour, financial attitude and financial trust-related questions data result calculated with the help of simple average, and the first result of financial knowledge start below.
Financial Literacy Table 1. Correct Answers to Knowledge Questions
| S. NO width="245" valign="top">Questions width="186" valign="top">Note width="51">Score | > 1 width="245" valign="top">I always use mental arithmetic to solve a simple division. width="186" valign="top">Open answer and correct answer are, therefore, a good pointer of practical skill width="51">90% | > 2 width="245" valign="top">I am assured in my understanding of financial ideas such as money managing, investments, and budgeting. width="186" valign="top">Many responses width="51">86% align="center"> align="center"> | > 3 width="245" valign="top">I understand how time variance could disturb the value of money is relative to the investment. width="186" valign="top">Many responses width="51">87% | > 4 width="245" valign="top">I know that high inflation means that cost of living is growing. width="186" valign="top">Many responses width="51">84% align="center"> | > 5> width="245" valign="top">I know the calculation of compounding interest. width="186" valign="top">Open response and a correct answer are, thus, a good pointer of practical proficiency width="51">94% align="center"> | > width="245" valign="top"> Total score width="186" valign="top">width="51"> 88% | |||||||||||||||
| S. No width="405">Questions width="74">Score | > 1 width="405">I have savings and investments suitable for the needs width="74">93% | > 2 width="405">I use my debit card to make money or buy things straight. width="74">72% | > 3 width="405">I track my monthly expenses. width="74">88% | > 4 width="405">I keep enough balances in my bank account. width="74">87% | > 5 width="405">I set long term goals and struggled to attain them. width="74">52% | > width="405"> Total Score width="74">78% | |||||||||||||||
| S. No width="426">Questions width="62">Score | > 1 width="426">I am pleased with my capability to meet my financial responsibilities. width="62">85% | > 2 width="426">I am pleased with the income potential my current job offers me. width="62">64% | > 3 width="426">I am pleased with my expenditure habits. width="62">80% | > 4 width="426">I am pleased with the level of debt I carry width="62">82% | > 5 width="426">I am satisfied with my current investment choices. width="62">72% | > width="426"> Total Score width="62">77% | |||||||||||||||
| S. No width="314">Questions width="117">Note width="50">No | > 1 width="314">Do you trust the agent to take care of your certain resources? width="117">Yes/no question width="50">98% | > 2 width="314">Does your agent provide you with the right information at the right time? width="117">Yes/no question width="50">93% | > 3 width="314">Does trust decline with age? width="117">Yes/no question width="50">65% | > 4 width="314">Does trust increase with a willingness to take investment risks? width="117">Yes/no question width="50">90% | > width="314"> Total Score width="117">width="50"> 86% | ||||||||||||||||
| width="60" nowrap="" colspan="2" valign="bottom"> Q 1 width="54" nowrap="" valign="bottom">Q2 width="54" nowrap="" valign="bottom">Q3 width="54" nowrap="" valign="bottom">Q 4 width="40" nowrap="" valign="bottom">Q 5 width="47" nowrap="" valign="bottom">Q6 width="51" nowrap="" valign="bottom">Q7 width="48" nowrap="" valign="bottom">Q8 width="54" nowrap="" valign="bottom">Q9 width="36" nowrap="" valign="bottom">Q10 | > Question 1 width="54" nowrap="" valign="bottom">1 width="54" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="40" nowrap="" valign="bottom"> width="47" nowrap="" valign="bottom"> width="51" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 2 width="54" nowrap="" valign="bottom">0.226 width="54" nowrap="" valign="bottom">1 width="54" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="40" nowrap="" valign="bottom"> width="47" nowrap="" valign="bottom"> width="51" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 3 width="54" nowrap="" valign="bottom">-0.0668 width="54" nowrap="" valign="bottom">0.2366 width="54" nowrap="" valign="bottom">1 width="54" nowrap="" valign="bottom"> width="40" nowrap="" valign="bottom"> width="47" nowrap="" valign="bottom"> width="51" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 4 width="54" nowrap="" valign="bottom">0.2997 width="54" nowrap="" valign="bottom">0.2553 width="54" nowrap="" valign="bottom">0.0624 width="54" nowrap="" valign="bottom">1 width="40" nowrap="" valign="bottom"> width="47" nowrap="" valign="bottom"> width="51" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 5 width="54" nowrap="" valign="bottom">0.0096 width="54" nowrap="" valign="bottom">0.0472 width="54" nowrap="" valign="bottom">0.1112 width="54" nowrap="" valign="bottom">0.0436 width="40" nowrap="" valign="bottom">1 width="47" nowrap="" valign="bottom"> width="51" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 6 width="54" nowrap="" valign="bottom">0.0894 width="54" nowrap="" valign="bottom">-0.0939 width="54" nowrap="" valign="bottom">-0.0902 width="54" nowrap="" valign="bottom">-0.0679 width="40" nowrap="" valign="bottom">0.1041 width="47" nowrap="" valign="bottom">1 width="51" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 7 width="54" nowrap="" valign="bottom">0.0288 width="54" nowrap="" valign="bottom">0.0328 width="54" nowrap="" valign="bottom">-0.1825 width="54" nowrap="" valign="bottom">0.0019 width="40" nowrap="" valign="bottom">-0.0333 width="47" nowrap="" valign="bottom">0.2751 width="51" nowrap="" valign="bottom">1 width="48" nowrap="" valign="bottom"> width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 8 width="54" nowrap="" valign="bottom">0.0584 width="54" nowrap="" valign="bottom">-0.0876 width="54" nowrap="" valign="bottom">-0.1154 width="54" nowrap="" valign="bottom">-0.1329 width="40" nowrap="" valign="bottom">0.0433 width="47" nowrap="" valign="bottom">0.5329 width="51" nowrap="" valign="bottom">0.2791 width="48" nowrap="" valign="bottom">1 width="54" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 9 width="54" nowrap="" valign="bottom">0.1791 width="54" nowrap="" valign="bottom">0.0054 width="54" nowrap="" valign="bottom">-0.0751 width="54" nowrap="" valign="bottom">-0.038 width="40" nowrap="" valign="bottom">0.1189 width="47" nowrap="" valign="bottom">0.5882 width="51" nowrap="" valign="bottom">0.3561 width="48" nowrap="" valign="bottom">0.76 width="54" nowrap="" valign="bottom">1 width="36" nowrap="" valign="bottom"> | > Question 10 width="54" nowrap="" valign="bottom">-0.1292 width="54" nowrap="" valign="bottom">0.0072 width="54" nowrap="" valign="bottom">-0.0269 width="54" nowrap="" valign="bottom">0.0774 width="40" nowrap="" valign="bottom">0.0694 width="47" nowrap="" valign="bottom">0.037 width="51" nowrap="" valign="bottom">0.3219 width="48" nowrap="" valign="bottom">0.0353 width="54" nowrap="" valign="bottom">0.077 width="36" nowrap="" valign="bottom">1 | height="0"> width="6"> width="54"> width="54"> width="54"> width="54"> width="47"> width="47"> width="51"> width="48"> width="54"> width="36"> | ||||||||||
| width="54" nowrap="" valign="bottom"> Q1 width="54" nowrap="" valign="bottom">Q2 width="48" nowrap="" valign="bottom">Q 3 width="56" nowrap="" valign="bottom">Q4 width="48" nowrap="" valign="bottom">Q5 width="48" nowrap="" valign="bottom">Q11 width="48" nowrap="" valign="bottom">Q12 width="48" nowrap="" valign="bottom">Q13 width="49" nowrap="" valign="bottom">Q14 width="36" nowrap="" valign="bottom">Q15 | > Question 1 width="54" nowrap="" valign="bottom">1 width="54" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="56" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 2 width="54" nowrap="" valign="bottom">0.226 width="54" nowrap="" valign="bottom">1 width="48" nowrap="" valign="bottom"> width="56" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 3 width="54" nowrap="" valign="bottom">-0.0668 width="54" nowrap="" valign="bottom">0.2366 width="48" nowrap="" valign="bottom">1 width="56" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 4 width="54" nowrap="" valign="bottom">0.2997 width="54" nowrap="" valign="bottom">0.2553 width="48" nowrap="" valign="bottom">0.0624 width="56" nowrap="" valign="bottom">1 width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 5 width="54" nowrap="" valign="bottom">0.0096 width="54" nowrap="" valign="bottom">0.0472 width="48" nowrap="" valign="bottom">0.1112 width="56" nowrap="" valign="bottom">0.0436 width="48" nowrap="" valign="bottom">1 width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 11 width="54" nowrap="" valign="bottom">0.0402 width="54" nowrap="" valign="bottom">-0.0423 width="48" nowrap="" valign="bottom">-0.0627 width="56" nowrap="" valign="bottom">-0.1532 width="48" nowrap="" valign="bottom">0.1408 width="48" nowrap="" valign="bottom">1 width="48" nowrap="" valign="bottom"> width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 12 width="54" nowrap="" valign="bottom">0.1346 width="54" nowrap="" valign="bottom">0.0662 width="48" nowrap="" valign="bottom">0.1281 width="56" nowrap="" valign="bottom">-0.0105 width="48" nowrap="" valign="bottom">0.1429 width="48" nowrap="" valign="bottom">0.6994 width="48" nowrap="" valign="bottom">1 width="48" nowrap="" valign="bottom"> width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 13 width="54" nowrap="" valign="bottom">0.1165 width="54" nowrap="" valign="bottom">0.0752 width="48" nowrap="" valign="bottom">0.1474 width="56" nowrap="" valign="bottom">0.0067 width="48" nowrap="" valign="bottom">0.043 width="48" nowrap="" valign="bottom">0.4573 width="48" nowrap="" valign="bottom">0.6651 width="48" nowrap="" valign="bottom">1 width="49" nowrap="" valign="bottom"> width="36" nowrap="" valign="bottom"> | > Question 14 width="54" nowrap="" valign="bottom">-0.0257 width="54" nowrap="" valign="bottom">0.0445 width="48" nowrap="" valign="bottom">0.1432 width="56" nowrap="" valign="bottom">-0.1122 width="48" nowrap="" valign="bottom">0.2373 width="48" nowrap="" valign="bottom">0.3483 width="48" nowrap="" valign="bottom">0.4476 width="48" nowrap="" valign="bottom">0.6204 width="49" nowrap="" valign="bottom">1 width="36" nowrap="" valign="bottom"> | > Question 15 width="54" nowrap="" valign="bottom">0.0905 width="54" nowrap="" valign="bottom">0.0132 width="48" nowrap="" valign="bottom">0.0741 width="56" nowrap="" valign="bottom">0.0009 width="48" nowrap="" valign="bottom">0.4002 width="48" nowrap="" valign="bottom">0.4002 width="48" nowrap="" valign="bottom">0.526 width="48" nowrap="" valign="bottom">0.4144 width="49" nowrap="" valign="bottom">0.1645 width="36" nowrap="" valign="bottom">1 |